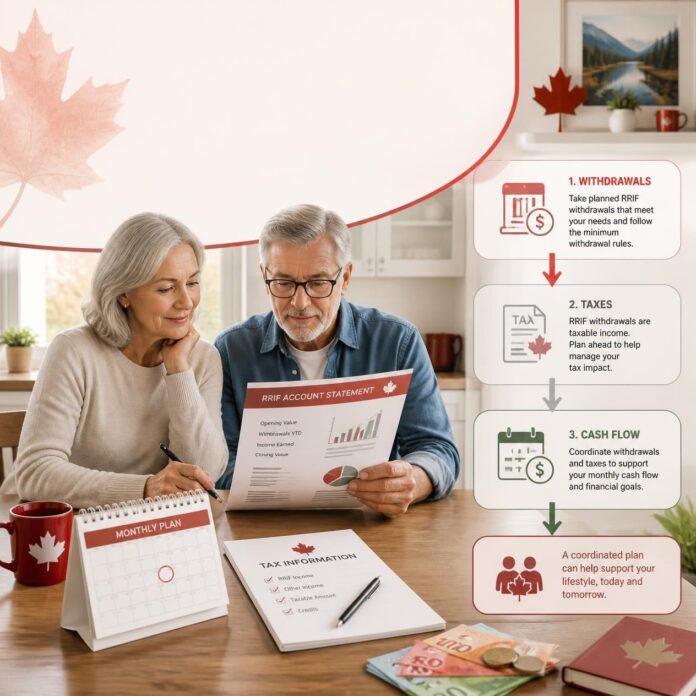


Retirement income can feel less predictable once employment income ends. Instead of one regular paycheque, many Canadians rely on a mix of CPP, OAS, workplace pensions, investment income, cash savings, and withdrawals from registered accounts. A solid plan connects those sources to real spending needs, rather than treating each account in isolation.
Understanding RRIF minimum withdrawal rates is an important starting point. Questrade, a Canadian provider of self-directed investing and managed portfolio services, explains how age-based factors, first-year timing, withholding tax, and tax reporting affect RRIF payments. Its educational resource is particularly useful for Canadians reviewing a RRIF held through an investment or retirement-income account, although individual tax outcomes still depend on personal circumstances.
What Changes When an RRSP Becomes a RRIF?
A Registered Retirement Income Fund, or RRIF, is a registered account designed to pay retirement income from savings that were previously held in an RRSP or another eligible registered plan. Unlike an RRSP, a RRIF does not accept new contributions. It requires minimum annual withdrawals beginning in the calendar year after the account is opened.
An RRSP must mature by December 31 of the year its holder turns 71. At that point, the usual options are to transfer the funds to an RRIF, use them to purchase an eligible annuity, or withdraw the money in cash. A direct transfer to a RRIF or eligible annuity generally avoids immediate withholding tax on the transfer itself, while future payments are normally taxable. The CRA describes how a registered retirement income fund works and outlines the rules governing payments from the plan.
How the Annual Minimum Fits Into a Retirement Budget
The RRIF minimum is a required baseline, not a recommendation for how much you should spend. For most account holders, the annual minimum is based on the RRIF’s value at the start of the year, which is generally the same as its value at the end of the preceding year, multiplied by the prescribed factor for the applicable age.
Prior to December 31, RRIF value × prescribed age-based factor = annual minimum payment
Your financial institution generally calculates the minimum and lets you choose how it is paid, such as monthly, quarterly, or annually. The payment schedule changes the timing of cash flow, not the total amount that must leave the RRIF during the year. A newly established RRIF generally has no required minimum payment until the following calendar year.
Build a Retirement Income Map Before Choosing Payments
Before setting a payment schedule, map out the full year rather than looking only at the RRIF balance. This gives each dollar of income a purpose and makes it easier to spot a possible tax shortfall.
- List reliable income, including CPP, OAS, workplace pensions, annuities, and recurring investment income.
- Estimate essential monthly expenses, such as housing, food, insurance, utilities, and medication.
- Separate flexible spending, including travel, gifts, and home projects.
- Review available RRIF, TFSA, non-registered investment, and cash balances.
- Estimate total taxable income for the calendar year.
- Choose a RRIF payment frequency that supports regular expenses without creating unnecessary withdrawals.
For example, someone whose essential expenses are covered by pension income and monthly RRIF payments may choose to use cash savings for a one-time roof repair. Taking an extra RRIF withdrawal simply because cash is needed quickly can increase taxable income when another available source would better suit the expense.
Withholding Tax Is Not the Same as Final Tax
Tax withheld from a RRIF payment is generally a prepayment toward your eventual tax bill, not a final calculation. Your tax return considers all income received during the year, along with deductions, credits, and your province or territory of residence.
That broader income picture can include RRIF payments, CPP and OAS, employment or self-employment income, workplace pension payments, interest, dividends, and realized investment income. A retiree may receive an additional RRIF withdrawal with tax withheld and still owe more at filing time if total income is higher than expected. Review projected annual income before requesting amounts above the minimum.
Government Benefits and Income-Tested Programs
Large RRIF withdrawals can affect income-tested benefits, credits, and the OAS recovery tax calculation. This does not mean every extra withdrawal creates a problem. It means the timing matters. Spreading planned withdrawals over several years may produce a different result than taking a large amount in one year.
Before withdrawing funds for a major purchase, compare the projected tax impact with alternatives such as existing cash, a TFSA withdrawal, or delaying discretionary spending. Benefit thresholds and tax rules can change, so current information should be checked before making a significant decision.
When Pension Income Splitting May Help Couples
Eligible pension income may be split between spouses or common-law partners through a joint tax election. For someone aged 65 or older at year-end, RRIF income can generally qualify. Up to 50% of eligible pension income may be allocated to the other spouse or partner, subject to the applicable rules.
The CRA’s pension income splitting rules explain eligibility, the joint election process, and possible effects on credits and benefits. Splitting can reduce one person’s net income while increasing the other’s, so couples should consider both tax brackets and individual income-tested programs.
Should You Withdraw More Than the Minimum?
A larger RRIF withdrawal can be reasonable when it supports a specific plan, such as a necessary home repair, health expense, charitable gift, family gift, or an effort to manage future taxable RRIF balances. It may also be appropriate when cash flow needs are consistently above the annual minimum.
However, extra withdrawals can create a higher tax bill, affect income-tested benefits, reduce assets available for later retirement years, or simply exceed actual spending needs. The question is not whether more than the minimum is always good or bad. It is whether the withdrawal supports a documented income, tax, and estate plan.
Common RRIF Mistakes to Avoid
- Waiting until December to arrange the required annual payment.
- Assuming withholding tax covers the final tax liability.
- Estimating taxes without including CPP, OAS, pension income, and investment income.
- Taking a large withdrawal without considering the benefit effects.
- Overlooking the option to use a younger spouse or common-law partner’s age when the election was properly made at RRIF setup.
- Failing to save account statements and T4RIF slips.
- Assuming a transfer is tax-deferred without confirming it is completed directly and correctly.
A Simple Year-End RRIF Checklist
- Confirm the account value used to calculate the year’s minimum.
- Check that the full minimum will be paid by December 31.
- Compare the total expected taxable income with the original plan.
- Review whether actual spending still supports planned extra withdrawals.
- Consider whether pension income splitting applies.
- Keep statements, tax slips, donation receipts, and other relevant records.
- Speak with a qualified tax professional before making an unusually large withdrawal.
Questions Readers Often Ask
Does a RRIF have to pay monthly?
No. Monthly payments can help with budgeting, but many plans also permit quarterly or annual payments.
Can a retiree withdraw more than the required amount?
Yes, but the additional amount is generally taxable and may affect benefits or credits.
Does the minimum payment count as taxable income?
RRIF payments are generally included in income for the year received.
Turn a Required Payment Into a Planned Income Stream
A RRIF minimum should be one part of a broader retirement-income plan. Review spending needs, taxes, government benefits, other account balances, and family goals early in 2026. With that full picture in place, the required payment becomes a more deliberate income stream rather than a year-end surprise.